For many people, retirement is viewed as the definitive conclusion of one’s earning years. After decades of early mornings, steady employment, and managing endless responsibilities, the transition into retirement often feels like a well-deserved time to finally slow down. However, a critical question often goes unaddressed: what happens to the capital you receive the moment you step away from your career?.
For John Ekene, this question became a tangible reality. John spent the majority of his professional life as a dedicated Mathematics teacher at a secondary school in Maitama, Abuja. For years, he made the daily commute from his home in Lugbe to Maitama, eventually becoming one of the most experienced and respected members of the school’s faculty. When he finally reached the age of retirement, he was presented with his gratuity: a total of ₦4 million.
To John, this sum represented far more than a simple bank balance; it was the culmination of decades of discipline, commitment, and personal sacrifice.
The Retirement Dilemma
At this stage of his life, John’s major financial burdens had largely subsided. His children had completed their education, his lifestyle was quiet and modest, and he had no immediate need for extravagant spending. He found himself at a crossroads with several options for his ₦4 million:
- Static Savings: Leaving the entire sum in a standard bank account.
- Immediate Distribution: Distributing the funds among family members.
- Personal Consumption: Spending the money on immediate personal desires.
- Active Re-investment: Finding a way to keep the capital productive.
John understood a fundamental truth about wealth: retirement from a job does not necessitate the retirement of one’s capital. He sought an investment that would remain productive without requiring him to return to the high-stress environment of active employment. This search led him to the concept of Fractional Ownership.
A Modern Approach to Real Estate Participation
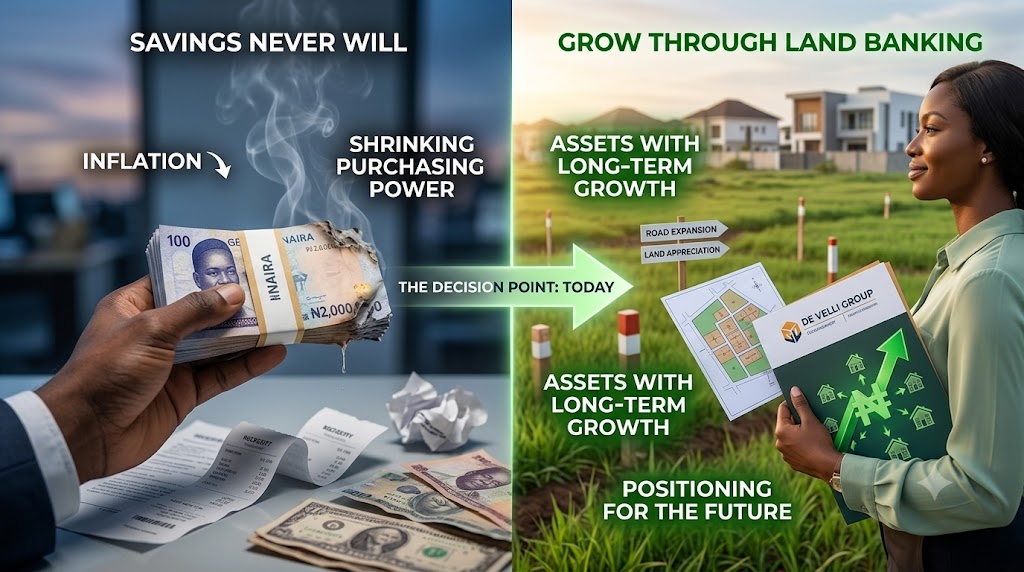
Fractional ownership allows multiple investors to collectively participate in high-value real estate assets by acquiring documented ownership interests. Instead of requiring the massive capital necessary to purchase an entire property alone, an investor can participate with a significantly smaller amount of capital while enjoying the benefits of professional management.
| Investment Allocation | Amount (₦) | Purpose |
| Growth-Focused Investment | ₦2,000,000 | De Velli Co-Fractional Ownership |
| Liquid Reserves | ₦2,000,000 | Personal Needs & Financial Security |
| Total Capital | ₦4,000,000 | Total Retirement Benefit |
For John, this model provided the perfect strategic balance. By investing half of his benefit into a fractional real estate opportunity, he ensured he was no longer depending entirely on a pension. He retained ₦2 million for liquidity and emergencies, while the other ₦2 million was positioned in an asset designed for long-term growth and potential rental income.
Breaking the Cycle of Financial Stagnation
John’s story highlights a challenge that many Nigerians will eventually face. A retirement benefit can provide immediate comfort, but without a strategic plan, even a substantial payout can gradually erode through everyday expenses, family requests, and the rising cost of living.
Investing a portion of retirement funds into carefully vetted assets creates an essential layer of financial security. This approach does not advocate for risking every Naira; rather, it encourages understanding one’s long-term needs and identifying opportunities to preserve and grow wealth.
John did not invest with the goal of becoming wealthy overnight. He invested because he wanted his money to have a continued purpose. His active working years had ended, but his financial journey had simply entered a new phase.
The Core Principles of Wealth Transition
- Passive Income Generation: Shifting from earning a salary to earning from assets that do not require daily management.
- Asset Protection: Utilizing real estate to hedge against inflation and preserve the purchasing power of retirement funds.
- Strategic Liquidity: Maintaining a balance between invested capital and accessible cash for personal peace of mind.
- Professional Oversight: Leveraging the expertise of firms like De Velli Group to handle maintenance, leasing, and regulatory compliance.
For those approaching retirement, receiving a pension, or simply looking for ways to make their savings more productive, fractional ownership offers a structured path to real estate exposure without the burdens of solo property management.
John’s story is a reminder that retirement is not the point where wealth creation must stop; it is the point where your money should finally begin working differently.
